Quick answer
Crypto is taxed as a capital asset in the UK. Each time you sell, swap, spend or give away a token, you make a disposal, and the gain is the pound value you received less the matched cost. Gains above your £3,000 allowance are taxed at 18% or 24% for 2026/27. Enter your trades above to see each gain and the tax.
Key facts
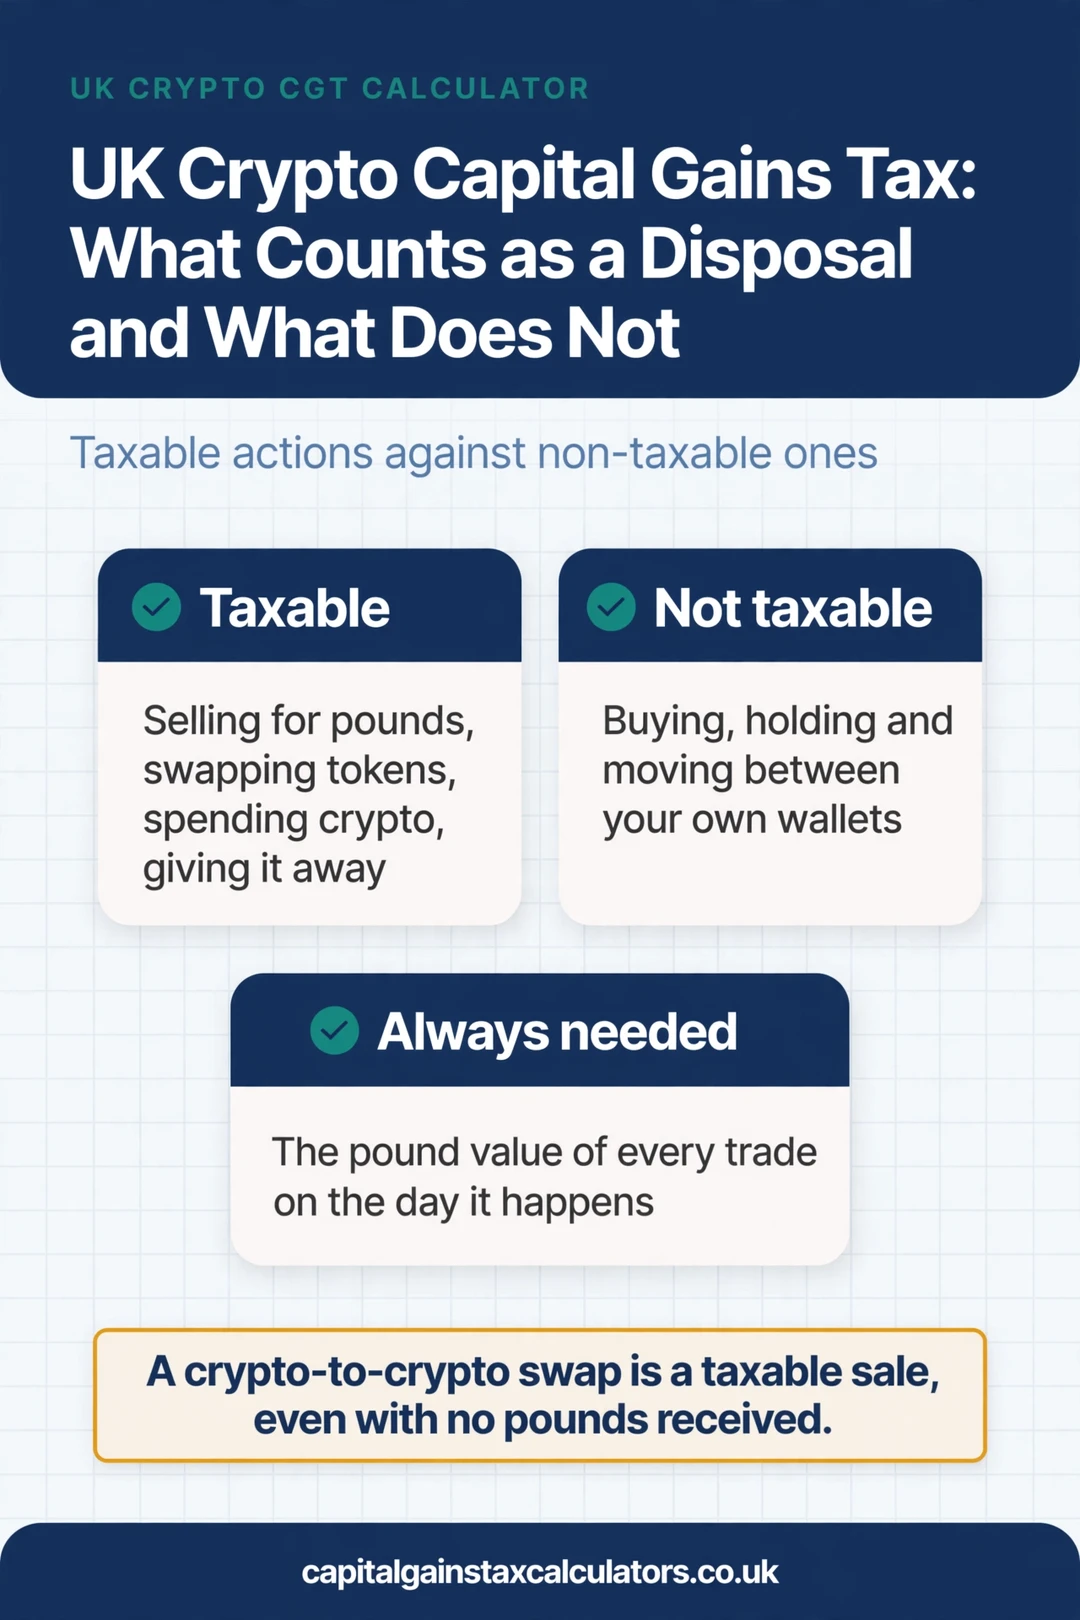
- Selling, swapping, spending and giving away crypto are all disposals. Buying and holding is not.
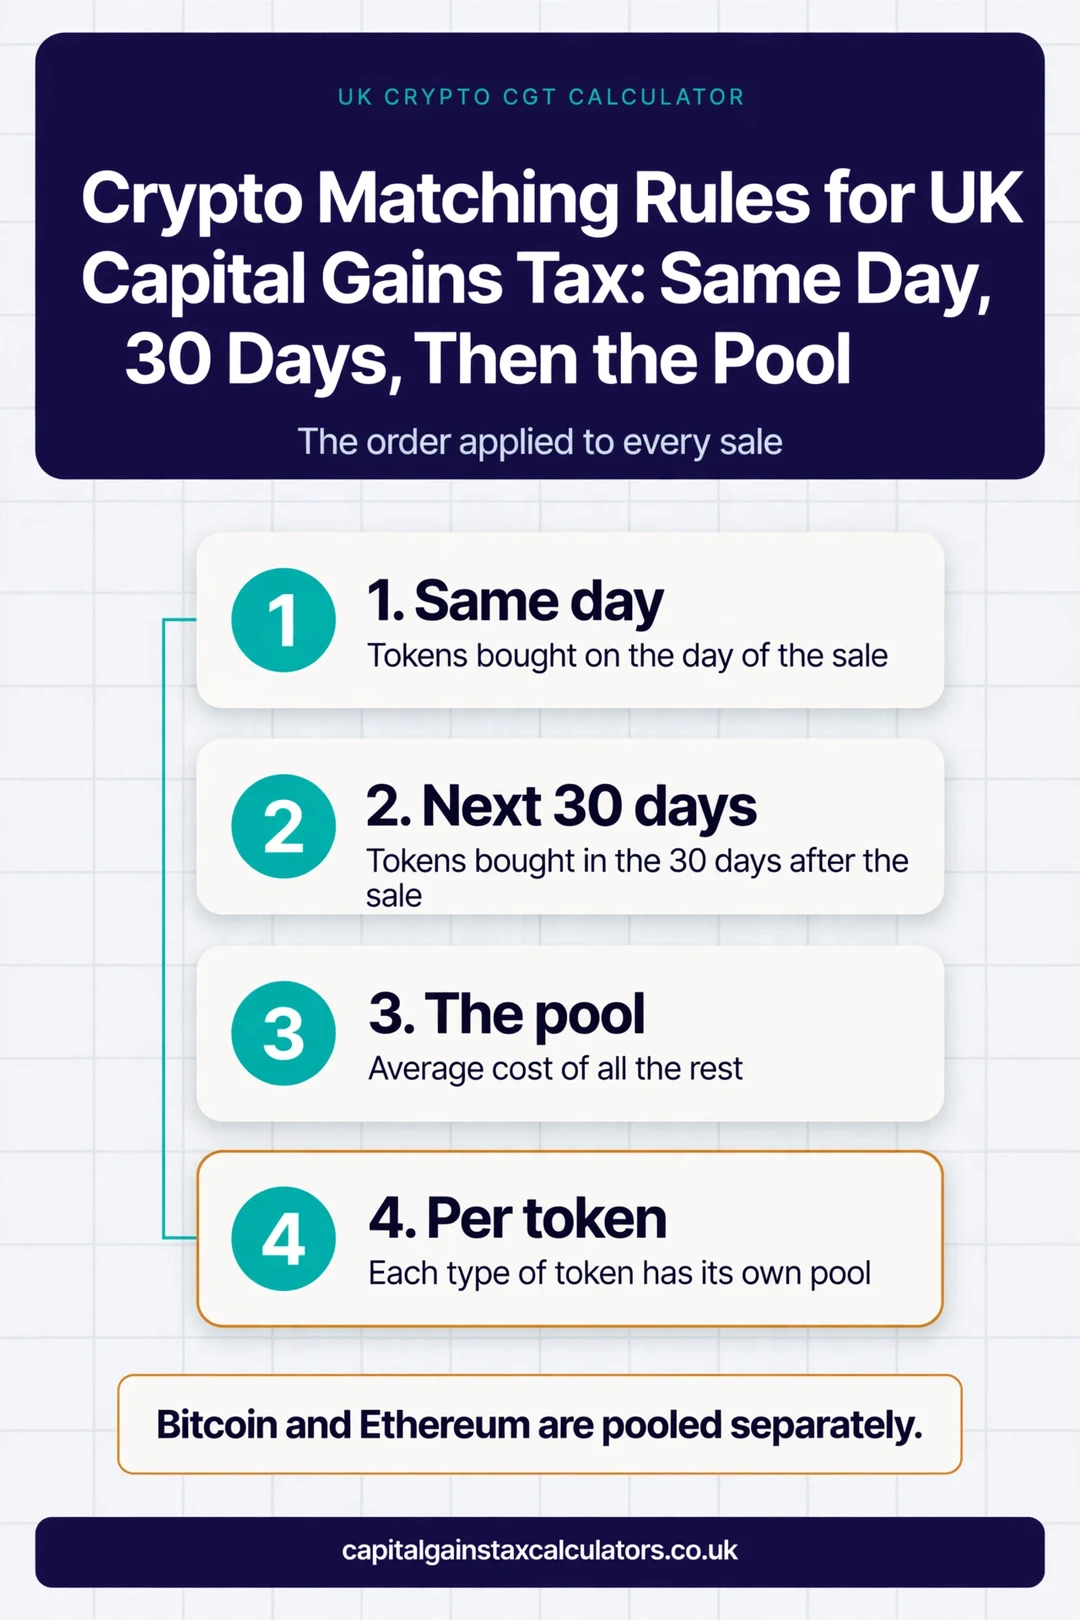
- Cost is pooled per token (for example, all Bitcoin in one pool) and matched same-day, then 30-day, then pool.
- Every amount must be in pounds at the time of the trade, including swaps between tokens.
- Gains are taxed at 18% or 24% after the £3,000 allowance in 2026/27.
- Mining, staking and airdrops can create Income Tax first, then a cost for later gains.
How the crypto calculator works
Add one row for each trade: the date, whether you bought or sold, the quantity, the total pound amount including fees, and the token name. The calculator groups trades by token, sorts them by date and applies HMRC’s three matching rules. You see the gain on every sale, your remaining pool, and an estimate of the tax on disposals made in 2026/27.
You can paste rows from a spreadsheet. Use one row per trade and give each token its own name, such as BTC or ETH. Swaps need two rows, as shown later on this page.
| Column | What to enter | Common error |
|---|---|---|
| Date | The day of the trade | Using the date of the transfer between wallets |
| Buy or sell | Direction of the trade | Leaving out swaps and spending |
| Quantity | The number of tokens | Rounding away small decimals |
| Amount | Pounds paid or received, with fees | Entering the value in another currency or a stablecoin |
| Token | A short name such as BTC | Typing different names for one token |
Worked example: selling Bitcoin bought twice
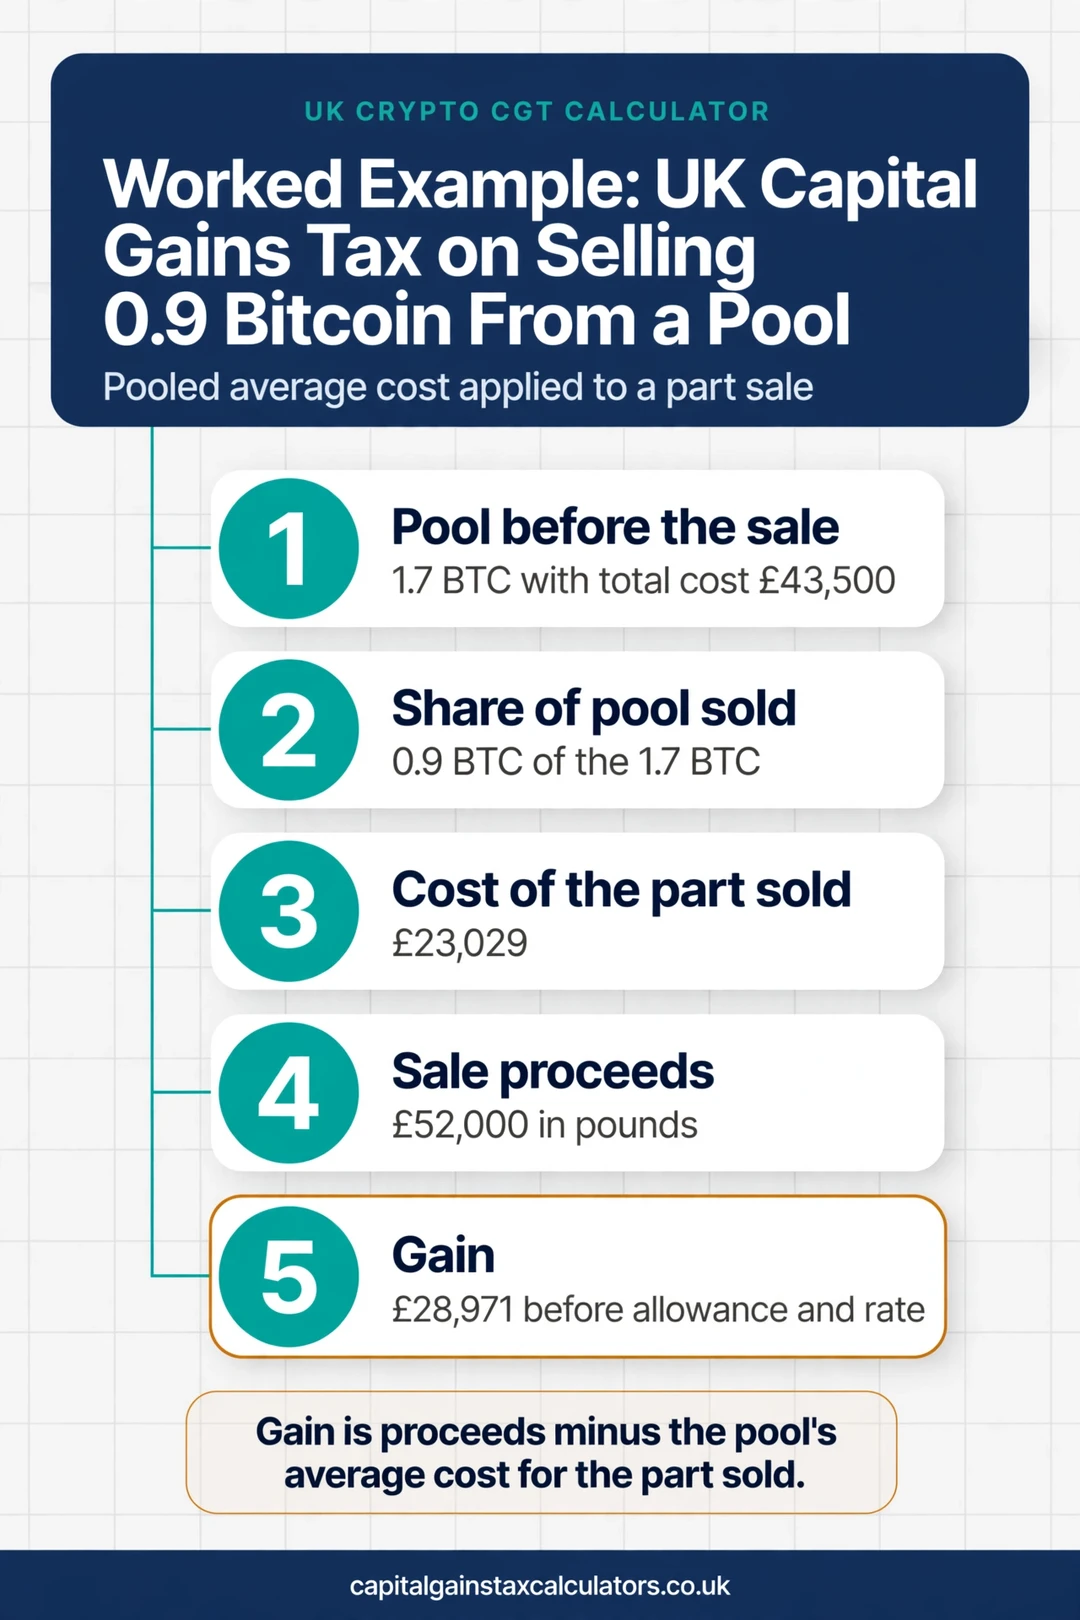
You buy 1.2 BTC for £21,000, then 0.5 BTC for £22,500 about a year later. In 2026/27 you sell 0.9 BTC for £52,000. Your income is £38,000.
Worked example
Gain on 0.9 BTC
- Pool before the sale: 1.7 BTC with a total cost of £43,500.
- Cost of 0.9 BTC: 0.9 / 1.7 x £43,500 = £23,029.
- Gain: £52,000 less £23,029 = £28,971.
- After the allowance: £25,971 is taxable, charged at 18% on £12,270 and 24% on £13,701.
- Capital Gains Tax: £5,497.
- Left in the pool: 0.8 BTC with a cost of £20,471.
On an income of £90,000, the same sale would cost £6,233, because the whole gain falls into the 24% band.
Swapping one token for another
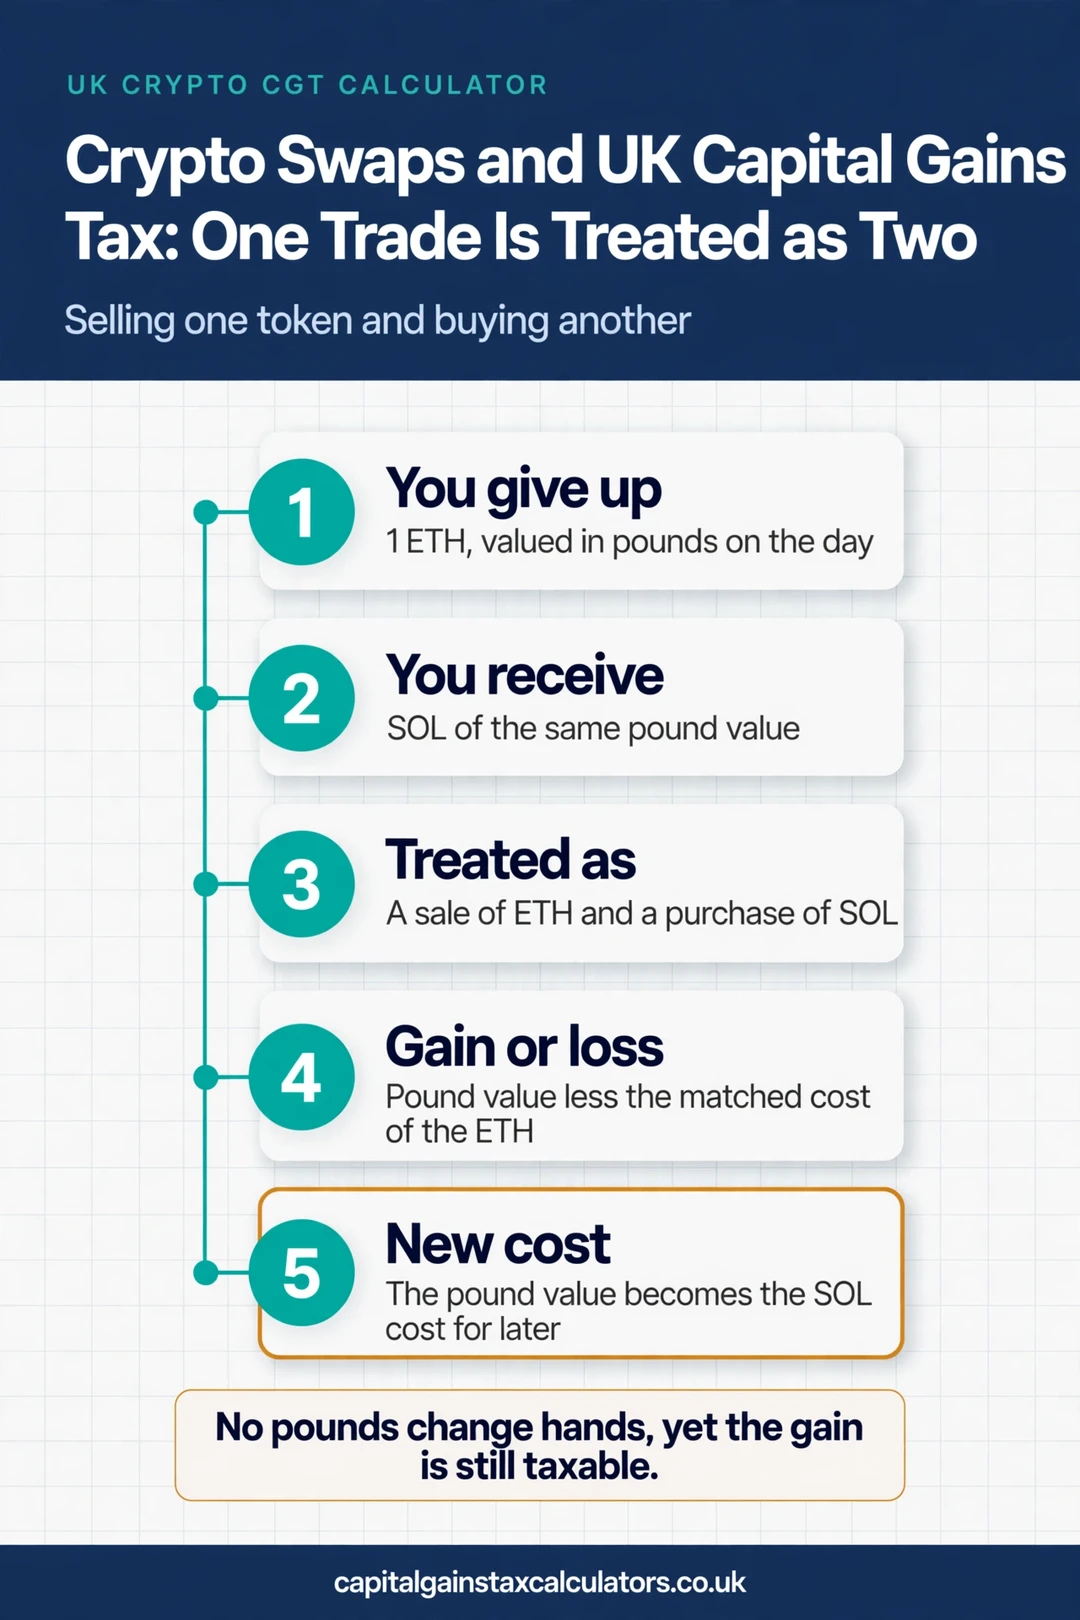
A swap is a disposal of the token you give up. Its value is the pound value of what you receive, worked out at the time of the swap. You also acquire the new token at the same value. Suppose you hold 2 ETH that cost £4,000 and swap 1 ETH for SOL worth £3,500.
| Step | Working | Result |
|---|---|---|
| Disposal of 1 ETH | Value received in pounds | £3,500 |
| Cost of that 1 ETH | Half of the pool cost of £4,000 | £2,000 |
| Gain on the swap | £3,500 less £2,000 | £1,500 |
| Cost of the new SOL | The same pound value | £3,500 |
Moving crypto between your own wallets or exchanges is not a disposal. Only the changes of ownership count. Keep the pound value of each swap from the day it happened.
Losses and the 30-day rule for crypto
A loss on one token can be used against gains on another in the same tax year. For example, buying 1 BTC for £40,000 and selling it for £30,000 produces a loss of £10,000. You must report the loss to HMRC to carry it forward.
The 30-day rule applies to crypto in the same way as to shares. If you sell and buy back the same token within 30 days, the sale is matched with the new purchase. In a simple case, selling 0.5 BTC for £18,000 and buying 0.5 BTC for £17,000 ten days later gives a gain of £1,000, based on the new cost, not the pool. Our bed and breakfast rule guide explains why.
Mining, staking, airdrops and rewards
Receiving crypto for work, mining or staking is usually taxed as income at its pound value when you receive it. That value then becomes your cost. Selling later may create a gain or a loss compared with that cost. Airdrops are usually only taxed as income if you did something to earn them. This calculator does not work out income. Enter the pound value you were taxed on as a purchase on the day you received the tokens.
What this calculator does not cover
- Income Tax on mining, staking, rewards and payments received for work.
- Lending, decentralised finance and liquidity pools, where the tax treatment depends on the arrangement.
- Non-fungible tokens that are not interchangeable, which may need separate treatment.
- Trades by a business trading in crypto as its trade.
- Exchange records that are missing or in foreign currency, which you must convert to pounds first.
Common mistakes with crypto gains
- Treating swaps as tax free. Every swap is a disposal.
- Forgetting spending. Paying for goods with crypto is a disposal at the pound value of the goods.
- Using foreign currency. Convert every amount to pounds on the day.
- Wallet transfers entered as sales. Moving your own coins is not a disposal.
- Ignoring fees. Network and exchange fees add to cost or reduce proceeds.
- No records. HMRC expects date, quantity, pound value and what the trade was for.
What to do next
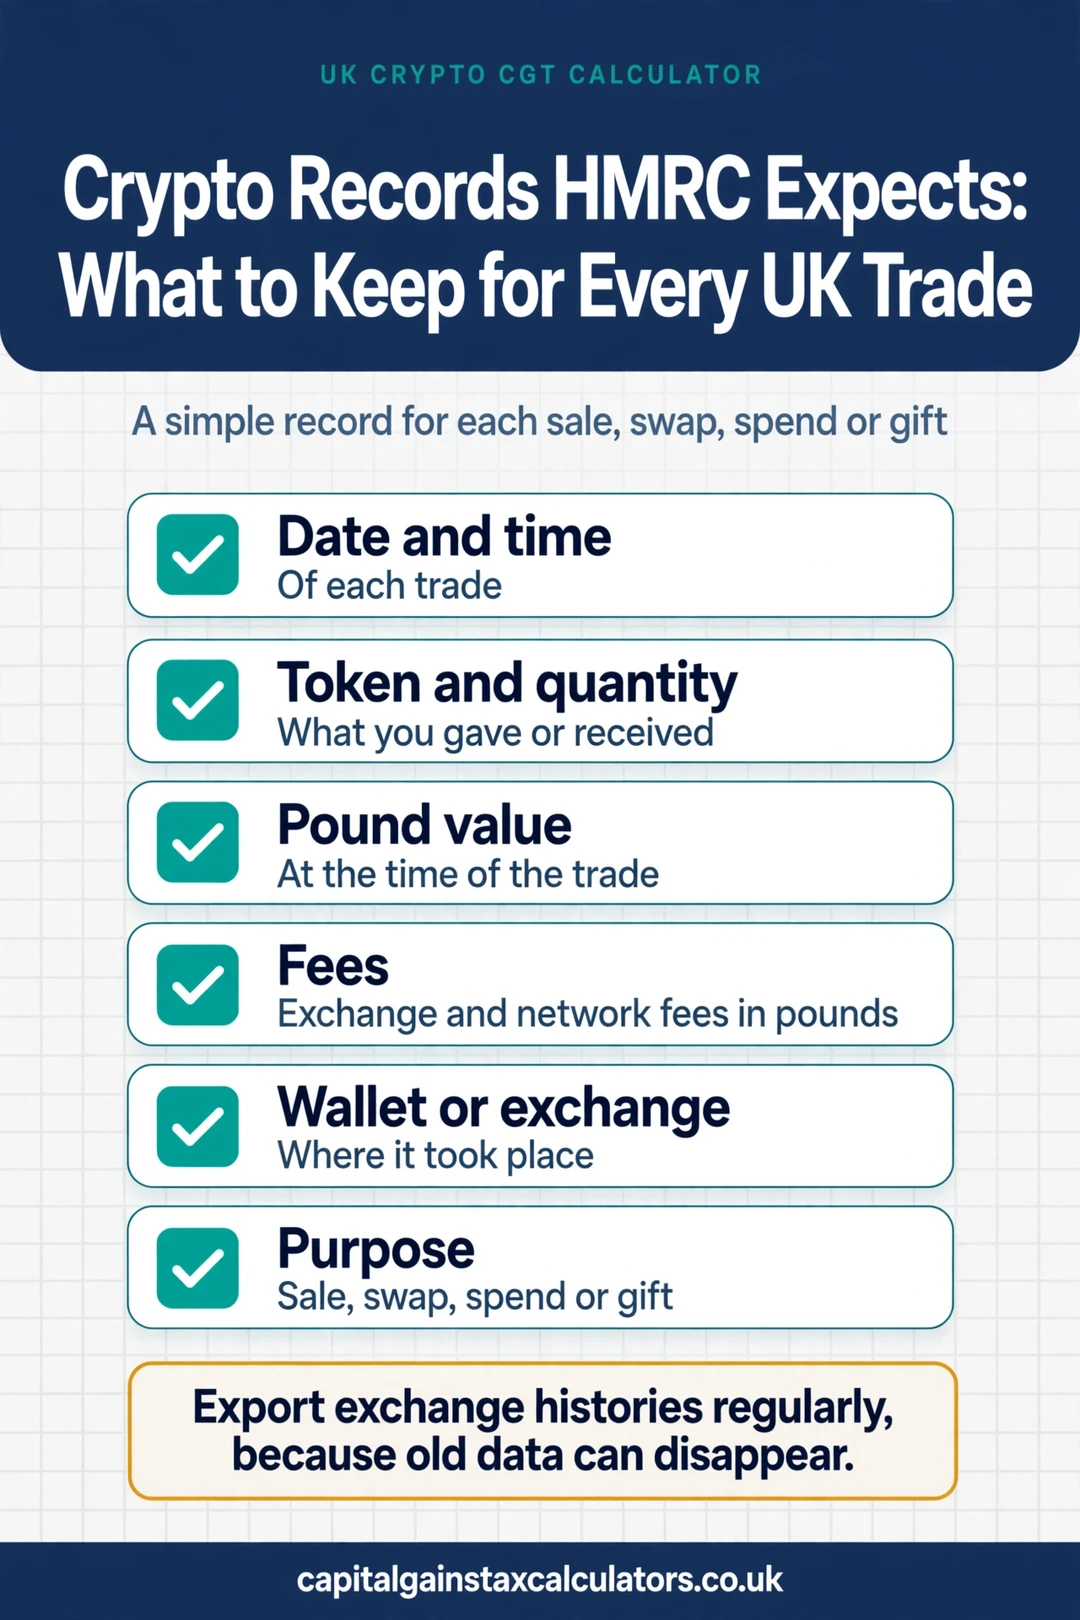
- Download the full transaction history from every exchange and wallet.
- Convert each trade to pounds and enter it in the calculator above.
- Check the pool balance against what you actually hold.
- Read the crypto tax guide for records and reporting.
- Report gains on your tax return, as set out in our reporting guide.
Frequently asked questions
Do I pay Capital Gains Tax on crypto in the UK?
Yes, if your total gains from all assets in a tax year are above £3,000 after losses. Gains are taxed at 18% or 24% for 2026/27, depending on your income. Small gains within the allowance are not taxed.
What counts as a crypto disposal?
Selling for pounds, swapping one token for another, spending crypto on goods or services, and giving it away to someone other than your spouse or civil partner. Buying, holding and transferring between your own wallets are not disposals.
How is the cost of crypto worked out?
HMRC pools tokens of the same type and uses the average cost of the pool, unless the same-day or 30-day rules apply. You cannot choose which coins you sold.
Do I need to report crypto if I made a loss?
You should report it if you want to carry the loss forward. Losses must be reported to HMRC within 4 years of the end of the tax year in which they arose.
Is a crypto-to-crypto swap taxable?
Yes. A swap is a disposal of the token you give up, valued at the pound value of what you receive on that day. The gain is that value less the matched cost.
Do I pay tax on staking rewards?
Rewards are usually Income Tax at their pound value when you receive them. That value is then your cost for a later Capital Gains Tax calculation.
Are gas and exchange fees deductible?
Fees paid to buy tokens add to cost. Fees paid to sell reduce your proceeds. Fees on transfers between your own wallets are not usually allowable.
How does HMRC know about my crypto?
HMRC receives data from exchanges and has the power to ask for more. It is sensible to report gains and keep full records rather than rely on not being checked.
Does this calculator support several tokens?
Yes. Give each token its own name and the calculator keeps a separate pool for each, applying the matching rules per token.
Is this the figure I should file with HMRC?
It is an estimate of the gains from the trades you entered. Check it against your exchange records, and take advice if you have staking, lending or decentralised finance activity.
Official sources
- GOV.UK: Tax on cryptoassets
- HMRC Cryptoassets Manual
- GOV.UK: Capital Gains Tax rates
- GOV.UK: Report and pay Capital Gains Tax
Related guides and calculators
This page gives general information for UK taxpayers and is not tax advice. Capital Gains Tax rules can change and your own circumstances matter. Check the latest rules on GOV.UK or with a qualified tax adviser before you act.